10 Common Credit Score Myths Debunked
Short Answer - Credit score myths often create confusion. Checking your own score doesn’t lower it, closing old cards can hurt it, and income isn’t included. Your score depends on payment history, credit utilisation, and account age. With consistent, responsible habits, it can always be improved over time.
As one of India’s licensed credit bureaus, CRIF HighMark sees how credit behaviour is reflected in credit reports and scores. Yet, several credit score myths, credit report myths and credit score misconceptions continue to create confusion. Here, we separate common myths from facts so you can understand what actually influences your credit score.
1. Myth: Checking Your Credit Score Lowers It
Some people avoid checking their score because they believe every check affects it.
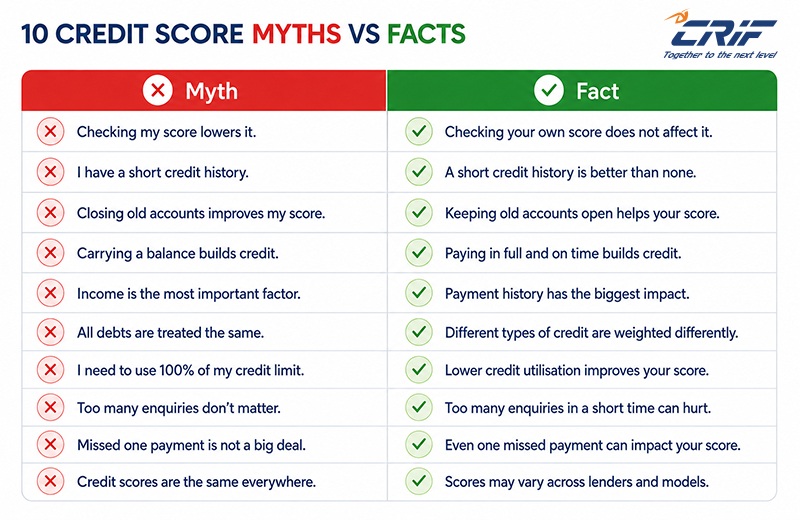
Fact: Checking your own score is a soft inquiry, it does not affect your score
When you check your own credit score, it is treated as a soft inquiry and does not lower your score. Hard enquiries lenders make when you apply for credit can affect your score. Checking your own report regularly helps you stay informed and spot inaccuracies.
2. Myth: Closing a Credit Card Improves Your Credit Score
Closing an unused card can seem like a sensible way to simplify your finances.
Fact: Closing a card reduces your available credit limit and can hurt your utilisation ratio
Closing a credit card reduces your total available credit. If your outstanding balances stay the same, your credit utilisation ratio increases. Closing an older card can also affect the age of your credit accounts. Consider these factors before closing a card.
3. Myth: You Need to Carry a Balance to Build Credit
Some people believe keeping unpaid credit card debt shows lenders that they actively use credit.
Fact: Paying your full outstanding balance each month builds credit without carrying costly debt
You do not need to carry a balance to build a positive credit history. On-time payments and responsible credit management matter more. Paying your full outstanding balance also helps you avoid unnecessary interest charges.
4. Myth: All Credit Inquiries Hurt Your Credit Score
Not every credit check affects your score the same way, although the terms are often used interchangeably
Fact: Only hard inquiries from lenders affect your score; checking your own score does not
A hard inquiry occurs when a lender checks your credit report as part of a credit application. Multiple credit applications in a short period can signal increased credit-seeking behaviour. Your own credit-score checks are soft inquiries and do not affect your score.
5. Myth: Your Income Determines Your Credit Score
It is easy to assume that a higher salary automatically translates into a higher credit score.
Fact: Income is not a credit score factor; repayment behaviour counts
Your income, savings and net worth do not form part of your credit score calculation. Your credit behaviour, including payment history, utilisation, account age, enquiries, and credit mix, matters. Lenders can still consider income separately when assessing a credit application.
Your income doesn't determine approval; your score does. See what lenders actually look for in our guide to personal loan approval with a low credit score.
From the Bureau's Desk:
At CRIF HighMark, we want to be clear: your income, savings, or net worth do not appear anywhere in your credit score calculation. We assess your credit behaviour, payment history, utilisation, account age, enquiries, and credit mix.
Myths aside, the truth about your credit score is in your report. Get yours from CRIF in under 2 minutes
6. Myth: One Late Payment Won’t Affect Your Score
A missed payment may seem insignificant if all your other payments are on time.
Fact: A late payment can negatively affect your credit score
Payment history is an important part of your credit profile. A payment reported as overdue can hurt your credit score, especially when the delay is significant. Set reminders or use auto-debits to stay on top of EMIs and credit card payments. The reality is more serious than most people realise, read our detailed breakdown of how even one late payment affects your credit score and what to do next.
7. Myth: You Have Only One Credit Score
Seeing different scores when checking your credit profile can make it seem like one of them must be wrong.
Fact: Your score can vary by bureau and by when it is calculated
Different credit bureaus use their own scoring models and the information available to them at the time of calculation. Scores can therefore differ. Focus on the overall health of your credit profile and the factors influencing it.
8. Myth: Debit Card Activity Affects Your Credit Score
Because debit cards are used for everyday transactions, some people assume they help build credit history.
Fact: Debit cards are not credit products; their transactions do not affect your credit score
Debit card transactions use money already available in your bank account. They do not represent borrowed credit and therefore do not build or lower your credit score. Credit products such as loans and credit cards are what contribute to your credit history.
9. Myth: Paying Off a Loan Immediately Boosts Your Score Significantly
Paying off a loan early is financially responsible, but it doesn't guarantee an immediate jump in your score.
Fact: Score improvement from loan closure is gradual, consistent repayment history matters more
Paying off a loan reduces your outstanding debt and closes the account once the lender reports it. However, your score reflects multiple aspects of your credit profile, so there is no guaranteed immediate increase. Maintaining a consistent repayment record remains important.
10. Myth: Your Credit Score Is Permanent and Cannot Change
A low score can feel like a permanent financial label.
Fact: Your credit score changes with your credit behaviour
Your credit score reflects the information available in your credit report at the time it is calculated. Timely repayments, responsible utilisation and careful credit applications can support improvement over time, while missed payments and excessive credit-seeking can work against it.
Want to see how your score changes with different financial decisions?
Kiran’s Case Study: How Closing Cards Affected His Score
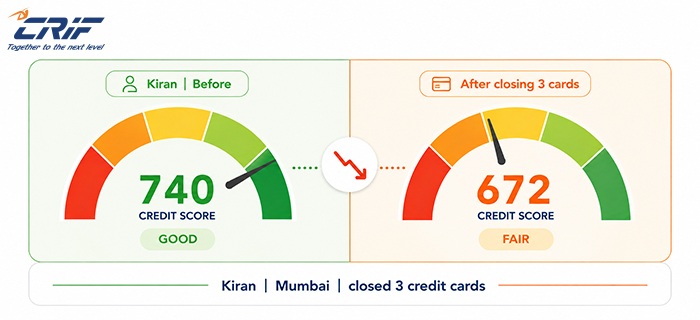
Kiran, a 31-year-old marketing manager in Mumbai, believed closing unused credit cards would improve his credit score. He closed three cards, reducing his total available credit limit from ₹3 lakh to ₹80,000. Within a month, his score fell from 740 to 672.
The reason was his higher credit utilisation. The same outstanding balance now represented a much larger share of his reduced credit limit. Kiran then focused on disciplined repayments and responsible credit use, and it took nine months to recover his score.
His key lesson was simple: closing a card can reduce available credit and affect the overall age of credit accounts. An unused card can often be kept open with a zero balance if there is no reason to close it.
CRIF Insight: Closing a credit card does not erase its history, but it immediately reduces your available credit limit. If you carry outstanding balances elsewhere, your utilisation ratio can increase.
Know the Facts Before You Borrow
Credit score myths can lead to unnecessary financial decisions, from avoiding credit checks to closing accounts that could support your credit history. Knowing how your credit score actually works helps you make informed choices, manage credit responsibly and build a stronger financial profile over time.
Frequently Asked Questions
If you’re still unsure about some of the common myths about credit score, these quick answers can help clear up the confusion.
1. Does checking your own credit score lower it?
No. Checking your own credit score is a soft inquiry and does not lower your score.
2. How many credit scores do you have in India?
You can have scores from different credit bureaus, and they can vary based on their scoring models and the information available.
3. Does income affect your credit score?
No. Income is not a factor in credit score calculation, although lenders can consider income separately when assessing applications.
4. How long does a late payment stay on your credit report?
The period for which repayment information remains on a credit report depends on the reporting and applicable data-retention practices. Check your credit report for the information currently reported.
5. Can a credit score go from bad to good?
Yes. Credit scores are not permanent. Consistent repayments, responsible credit utilisation and disciplined credit behaviour can help improve your credit profile over time.
Now that you know what actually moves your score, read our complete guide on how to improve your credit score, with steps that are proven to work.
Disclaimer: This article is intended for general educational purposes only and should not be considered financial or legal advice. Credit reporting timelines, CRIF Credit Score calculations, and lender policies may vary. Always verify your account details with your lender and refer to your latest CRIF HighMark credit report for the most accurate information.
Written by: CRIF Editorial Team | Published: August 2026 | Last Updated: August 2026