How to Increase Your Credit Score: 8 Proven Strategies
Your credit score plays a significant role in your financial profile, influencing your ability to qualify for loans, credit cards, and other forms of credit. A strong credit score improves both your chances of approval and can also help you secure more favourable interest rates and lending terms.
If you're already making payments on time and keeping your credit utilisation below 30%, you're on the right path to credit score improvement. However, these are just some of the factors that contribute to a healthy credit score. Read on to discover the remaining steps that can help you build a stronger and more reliable credit history.
What Is a Good Credit Score in India?
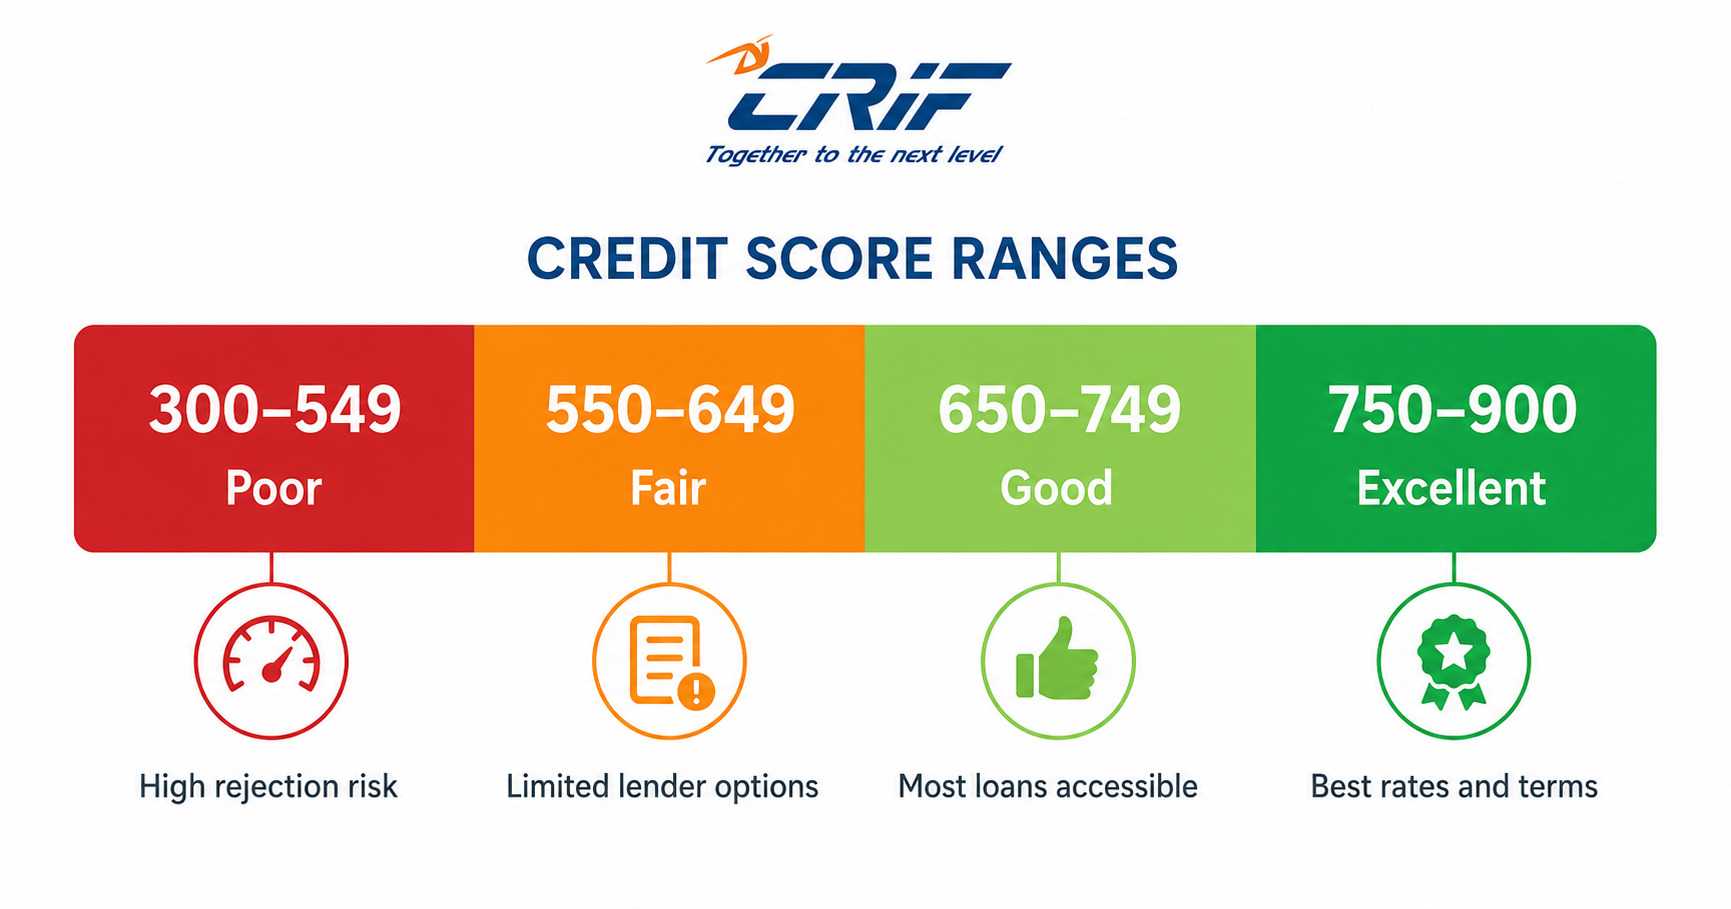
Credit scores typically range from 300 to 900. Here’s a credit score guide for your reference:
| Score range | Category |
|---|---|
| 300 – 625 | Poor |
| 625 – 750 | Fair |
| 750 - 800 | Good |
| 800 - 900 | Excellent |
A score of 750 or above generally puts you in a strong position for loan and credit card approvals, often with better interest rates and fewer conditions attached.
While lenders may view scores below 750 as carrying more risk, this doesn't mean approval is out of reach. With the right steps and financial habits, you can steadily improve your score and strengthen your chances of securing favourable credit terms.
8 Ways to Improve Your Credit Score
Improving your credit score is usually the result of consistent financial habits rather than quick fixes. Here are 8 ways to improve your credit score:
1. Make On-Time Payments
If you're wondering how to improve your credit score, making all your payments on time is one of the most effective steps you can take. Lenders review your payment history, as it reflects your ability to manage credit responsibly. To avoid missing payments, consider setting up auto-pay or payment reminders. If you, however, do miss a payment, clear the outstanding amount as soon as possible.
If you've missed payments in the past, here's a step-by-step guide to improve your payment history and reduce the impact on your score.
2. Keep Your Credit Utilisation Below 30%
Credit utilisation ratio is the percentage of your available credit limit that you're currently using. It's the second most influential factor in your score, and it's also one of the fastest to fix.
The ideal credit consumption level is less than 30% because keeping a minimal utilisation ratio shows lenders that you're not in a financially dire position. For instance, if your current credit limit is ₹50,00,0 then your transactions should be below ₹15,000 during the billing cycle.
From the Bureau's Desk:
At CRIF High Mark, we observe that borrowers who maintain credit utilisation below 30% are significantly more likely to cross the 750 score threshold within 12 months compared to those who consistently use over 60% of their limit.
3. Start Building Your Credit History Early
A lack of credit history (never taken a loan or used a credit card) isn't necessarily a bad thing. But it does complicate a lender's judgement when assessing your repayment behaviour. So, begin your credit journey at an earlier stage and work towards credit score improvement.
If you already have older credit cards, consider keeping them active even if you don't use them frequently because they anchor your credit history length and improve your credibility.
4. Don't Close Your Oldest Account
The length of your credit history is another important factor affecting your credit score. An account that has been well-managed for several years shows consistency and reliability. Shutting down an account you’ve held for more than 5 years could result in a reduction of your credit score by 10 to 20 points.
5. Diversify Your Credit Mix
Lenders prefer accounts that maintain a healthy mix of unsecured credit (such as credit cards) and secured credit (such as home loans or two-wheeler loans). This combination of different credit types shows your ability to manage multiple forms of borrowing. If you already possess a credit card and are considering a secured loan, this credit mix will work in your favour.
If you don't have a credit card, you can still build a strong profile. Find out how to improve your credit score without a credit card using secured loans and other options.
6. Limit New Credit Applications
Excessively applying for new credit in a short period of time can temporarily reduce your credit score. Lenders run a hard inquiry on your report each time you apply for new credit. Too many requests might lead to a temporary dip in your score and suggest you might be in financial trouble.
Better approach:
- Use eligibility checkers; these run a soft inquiry that doesn't affect your score.
- Apply for new credit only when necessary.
- Space out applications over time.
- Before applying, check your credit score online to see if you’re likely to be approved.
7. Dispute Errors in Your Credit Report
Credit reports, at times, could demonstrate errors such as an incorrect account status, a duplicate account appearing twice, or an outdated address linked to an old loan. These errors could reduce your overall credit score.
To avoid these errors, you must periodically check your credit score online along with the detailed report. In case you detect any errors, immediately raise a dispute directly with CRIF Credit Information Services Pvt. Ltd. (formerly CRIF High Mark Credit Information Services Pvt. Ltd.) along with supporting documents.
8. Become an Authorised User on a Family Member's Account
If you’ve just begun your credit journey or are rebuilding it, you can improve your credit score by becoming an authorised user on a parent or spouse’s account whose credit history is strong and positive. Their long history of on-time payments and low utilisation will positively impact your own credit report.
How Long Does It Take to Improve Your Credit Score?
There are no shortcuts, but there is a realistic timeline:
- Utilisation fixes: These show up fastest, often within 1-2 billing cycles of bringing your balance down.
- Payment history repair: This takes longer, typically 6-12 months of consistent, on-time payments.
- Building a score from scratch: This takes the longest, usually 12–18 months with a healthy mix of credit and regular repayment.
To improve your credit score, consistency is crucial. But, if you need a faster result, read our breakdown of whether your credit score can increase in a month to find out what's realistically possible.
From the Bureau's Desk:
Based on bureau data, consistent on-time payments over 6 consecutive months produce the most measurable score improvement for borrowers recovering from missed payments. Utilisation reduction shows faster results, often within 1-2 billing cycles.
Case Study: How Rahul Improved His Credit Score from 622 to 741
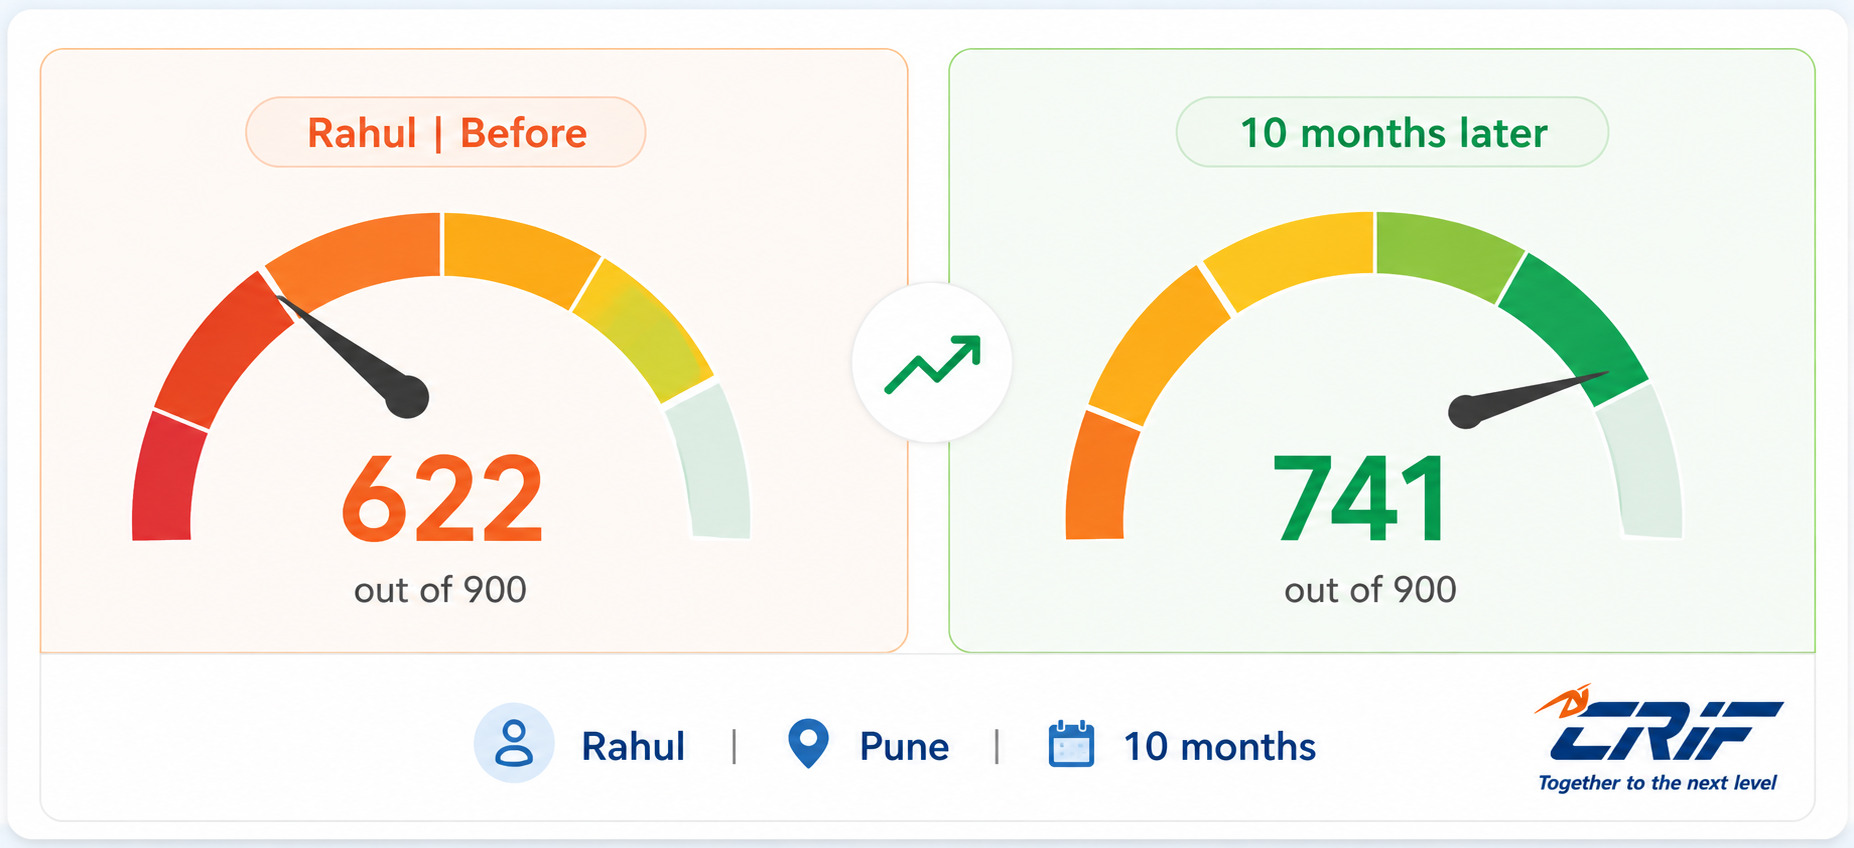
Rahul, a 28-year-old marketing executive from Pune, missed two credit card payments in 2023. His score dropped to 622, and a two-wheeler loan application was then rejected.
Instead of ignoring the issue, Rahul made three crucial changes;
- He set up auto-pay on his credit card.
- He cut utilisation from 78% to 22%.
- He also did not apply for any new credit during this period.
Ten months later, his score had climbed to 741, and he was approved for a personal loan at a competitive rate.
Insight:
Rahul's credit report showed that payment history and credit utilisation together accounted for over 70% of his score drop and his recovery. Addressing these factors delivers the fastest improvement.
Strong Credit Is Built One Step at a Time
Improving your credit score doesn’t happen overnight, but consistent financial discipline can make a meaningful difference over time.
Remember, every responsible financial decision contributes to a stronger credit profile and can help unlock better borrowing opportunities in the future. For a deeper understanding of your credit health, you can access your credit report through CRIF Credit Information Services Pvt. Ltd. (formerly CRIF High Mark Credit Information Services Pvt. Ltd.). and stay informed about your progress.
Frequently Asked Questions
1. How can I improve my credit score quickly?
The fastest way to improve your credit score is by lowering your credit utilisation by paying down balances before your statement date, which can show results within 1–2 billing cycles.
2. Does checking my own credit score lower it?
No. Checking your own credit score is a soft inquiry and has no impact on your score, regardless of how often you do it.
3. How long does it take to build a good credit score from scratch?
For someone with no prior credit history, it typically takes 12–18 months of responsible credit use, a mix of on-time payments and low utilisation to establish a solid score.
4. Will closing a credit card hurt my credit score?
Closing a long-held card shortens your average credit history and reduces your total available credit.
5. What credit score is needed for a personal loan in India?
Requirements vary by lender, but a score of 750 or above significantly improves your chances of approval and access to better interest rates.
Disclaimer: This article is intended for general educational purposes only and should not be considered financial or legal advice. Credit reporting timelines, CRIF Credit Score calculations, and lender policies may vary. Always verify your account details with your lender and refer to your latest CRIF HighMark credit report for the most accurate information.
Written by: CRIF Editorial Team | Published: July 2026 | Last Updated: July 2026