What Is a Good Credit Utilisation Ratio? (The 30% Rule Explained)
Short Answer - A good credit utilisation ratio is generally below 30%, with 10–20% being ideal. Calculate it by dividing your total outstanding balance by your total credit limit. Keep utilisation low by paying early, splitting expenses, tracking spending, and regularly monitoring your credit score.
Of all the factors that influence your credit score, your ideal credit utilisation ratio is one of the fastest to change and one of the quickest to impact your score. Lowering it can help your credit score recover within a single billing cycle, while high utilisation can cause your score to fall just as quickly. That is why understanding what a good credit utilisation ratio looks like and how to achieve it can make a significant difference to your overall credit health.
What Is Credit Utilisation Ratio?
Credit card[PR3.1] utilisation is the percentage of your total available credit that you're currently using. It's calculated across all your credit cards combined, not per card. So if you're asking what credit utilisation is, it's simply: how much of your combined credit limit is tied up in outstanding balances, expressed as a percentage. The lower the number is, the more "room" lenders see between what you can borrow and what you actually use.
How to Calculate Your Credit Utilisation
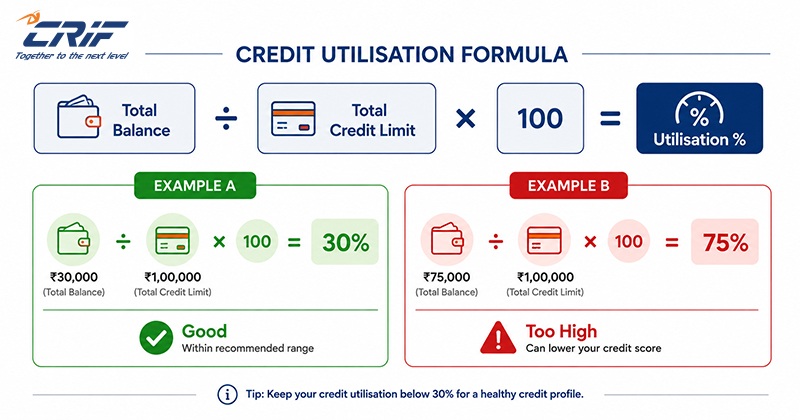
Calculating your credit utilisation ratio is simple. Divide your total outstanding balance by your total credit limit, then multiply the result by 100.
The formula is: (Total Outstanding Balance ÷ Total Credit Limit) × 100 = Credit Utilisation %
| Total Outstanding Balance | Total Credit Limit | Credit Utilisation | What It Means |
|---|---|---|---|
| ₹30,000 | ₹1,00,000 | 30% | Good |
| ₹75,000 | ₹1,00,000 | 75% | High |
For a complete step-by-step formula with worked examples across multiple cards, see our guide on how to calculate your credit utilisation ratio.
How Much of Your Credit Limit Should You Use?
A lower credit utilisation ratio generally indicates that you are using a smaller portion of your available credit, while a higher ratio can signal greater reliance on credit
| Utilisation Range | Zone | What It Signals |
|---|---|---|
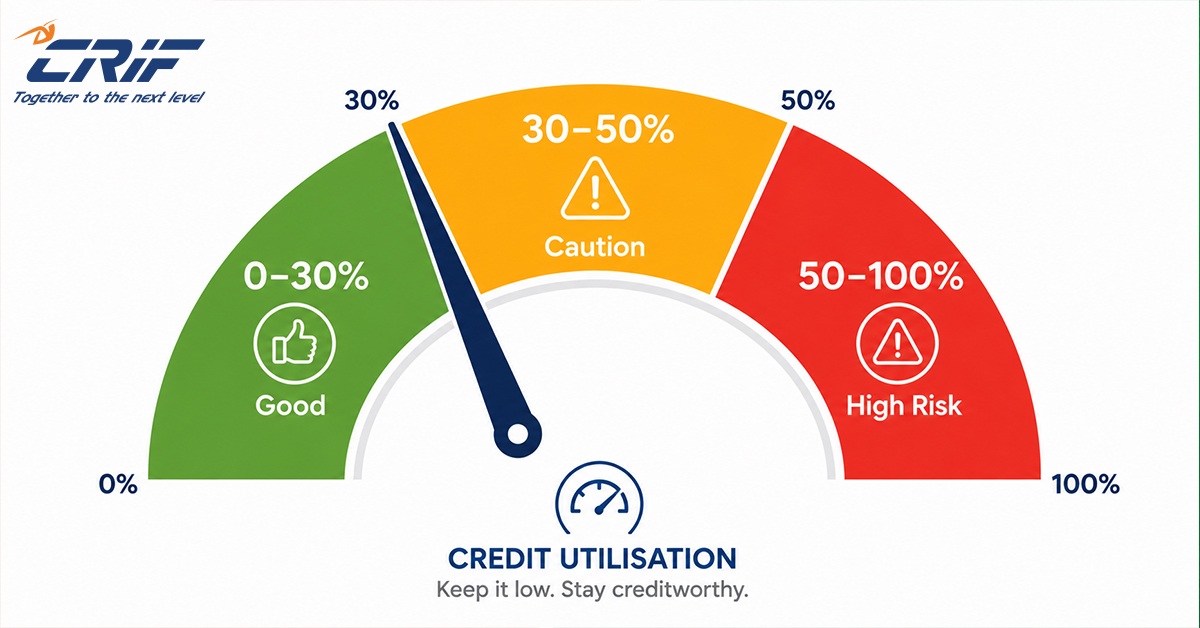
| Below 30% | Good | Healthy borrowing behaviour |
| 30% – 50% | Caution | Lenders may start noticing dependency on credit |
| Above 50% | High risk | Can actively pull your score down |
Is 0% credit utilisation good or bad?
A 0% credit utilisation ratio is not always ideal either. If you stop using your credit cards completely, credit bureaus may have less recent repayment activity to assess. Keeping your card active with small, manageable purchases and paying them on time can help maintain a positive credit history.
Read our guide on whether zero credit utilisation affects your credit score before deciding to stop using your card entirely.
What if your utilisation regularly goes above 50%?
Consistently crossing 50% credit utilisation signals to lenders that you may be relying heavily on credit to cover regular expenses. It does not mean you have missed a payment or are managing your finances poorly, but a high utilisation ratio can make you appear more credit dependent. If this pattern continues, it may also put downward pressure on your credit score, especially when reported balances remain high over time.
How Does Credit Utilisation Affect Your Credit Score?
Your credit utilisation ratio gives credit bureaus and lenders an indication of how much of your available credit you are currently using. A consistently high ratio can make your credit profile appear more dependent on borrowed funds, which may affect your score even when you make every payment on time.
Utilisation can also change quickly because your reported balance can vary from one billing cycle to the next. If you pay down a high balance, your utilisation can improve when you report a lower balance. This makes it one of the credit score factors you can actively manage without waiting months for your credit profile to change. Payment timing can also make a difference. Paying your bill on time is essential, but if you regularly carry a high balance, making an extra payment before the balance is reported can help lower your reported credit utilisation.
From the Bureau's Desk
Credit utilisation is one of the fastest-moving variables in a credit score. At CRIF HighMark, we see scores drop by 30–50 points when a cardholder consistently uses above 70% of their limit, and recover by a similar margin within 2–3 months once they bring usage back below 30%. Unlike payment history, which takes months to rebuild, utilisation changes show up almost immediately after the next billing cycle.
How to Keep Your Credit Utilisation Below 30%
Keeping your credit utilisation low does not always require major changes to your spending. A few simple habits can help you manage your reported balance more effectively.
- Pay before your statement closing date, not just the due date: Your credit report reflects the balance reported around the statement closing date, not simply whether you paid by the due date. If you pay in full but only after the statement closes, your report could still show a high balance. Consider paying down or splitting your payments before the statement closes.
- Spread purchases across cards or split a large payment mid-month: If you have multiple cards, distribute your spending instead of putting most of it on one card. With a single card, making a payment mid-cycle can help keep the balance lower rather than waiting until the due date.
- Request a credit limit increase, but only if you will not spend more: A higher credit limit can lower your utilisation percentage for the same level of spending. However, increasing your limit while also increasing your spending defeats the purpose.
For more practical strategies, read our dedicated guide on how to keep your credit utilisation ratio low.
From the Bureau's Desk
One commonly overlooked detail: your credit report reflects your balance on the statement closing date, not the payment due date. If you pay in full but only after the statement closes, the balance on your report could still look high. Pay down or split payments before your statement closes, not just by the due date.
A Realistic Example: Vikram, Mumbai
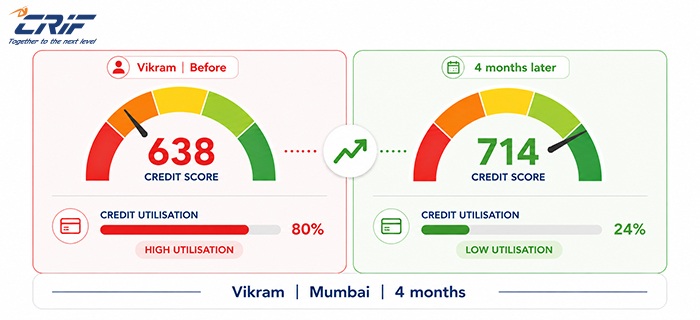
Vikram, a 30-year-old software engineer in Mumbai, held two credit cards with a combined limit of ₹2,00,000. His monthly spending averaged ₹1,60,000 -an 80% utilisation. Despite never missing a payment, his score had been stuck at 638 for over a year.
What he changed:
- Shifted expenses to debit card and UPI.
- Brought credit card spends to ₹48,000/month (24% utilisation).
- Split one large payment mid-month, before his statement closing date.
Outcome: Credit score improved from 638 to 714 over 4 months. As a result, he was approved for a personal loan he had previously been rejected for.
Keep Your Credit Utilisation in Check
Your credit utilisation ratio is one credit factor you can actively manage. Keeping balances under control, making payments before your statement closes, and avoiding unnecessary reliance on your available limit can help maintain a healthier credit profile. You do not need to avoid using your credit cards altogether. The goal is to use them responsibly, keep utilisation manageable, and pay your bills on time.
Your CRIF Credit Report shows your credit utilisation, payment history, and every factor affecting your score, all in one place.
Frequently Asked Questions
1. What is a good credit utilisation ratio in India?
Generally, keeping your good credit utilisation ratio below 30% of your total credit limit is considered healthy by lenders and credit bureaus.
2. What does "limit utilised" mean on my credit card statement?
It's the portion of your credit limit currently in use, shown as a percentage, the same figure your credit report uses to calculate your utilisation ratio.
3. Is it better to have 0% credit utilisation or 10%?
A small, regularly repaid utilisation (around 10%) is generally viewed more favourably than 0%, since it shows active, responsible credit use.
4. How quickly does credit utilisation affect my credit score?
Utilisation is one of the fastest-changing factors; shifts can reflect in your score within one or two billing cycles, once your statement is generated.
5. Does having multiple credit cards help with credit utilisation?
Yes, as long as you don't increase your overall spending. More available credit, used the same way, naturally lowers your utilisation percentage.
Disclaimer: This article is intended for general educational purposes only and should not be considered financial or legal advice. Credit reporting timelines, CRIF Credit Score calculations, and lender policies may vary. Always verify your account details with your lender and refer to your latest CRIF HighMark credit report for the most accurate information.
Written by: CRIF Editorial Team | Published: August 2026 | Last Updated: August 2026