Does Your Credit Score Affect Education Loan Approval in India?
Short Answer - An education loan affects your credit score like any other debt. Timely EMI payments can boost your score, create a good credit mix, and build a long credit history, while missed payments or defaults can lower your score and impact co-borrowers’ credit as well.
Most students assume an education loan gets approved purely on the strength of the course and the college. In reality, approval often hinges on something[PR3.1] few applicants think to check first: your education loan credit score, or your co-applicant's. It's a three-digit number, usually between 300 and 900, that tells a lender how reliably you or your co-applicant has repaid credit in the past, and it can matter as much as your admission letter. So before you start comparing interest rates, it helps to know what lenders actually check, what score gets you approved, and what to do if yours isn't there yet.
What Credit Score Do Lenders Look for in Education Loan Applications?
Since most students are applying for credit for the very first time, the credit score required for an education loan generally isn't about the student's file alone. In practice, it's decided by the strongest credit profile on the application, usually that of a parent or guardian applying as a co-applicant.
- A strong, well-established score signals reliable repayment behaviour and can improve both approval odds and the interest rate offered.
- A thin or patchy credit file, frequent late payments, or a recent default makes lenders cautious, even when the course and college are strong.
- Beyond the score itself, lenders also weigh income stability and repayment capacity before deciding how much to sanction.
For a broader look at how your credit score affects loan approval across all loan types, see our complete guide.
Minimum Credit Score for an Education Loan in India
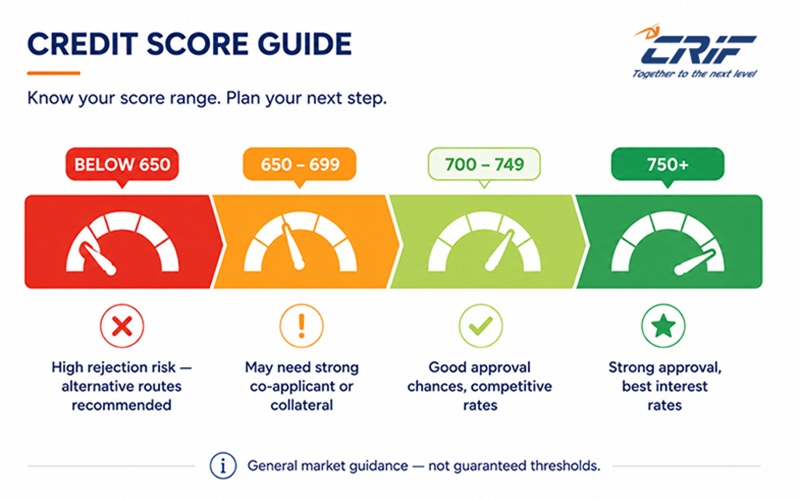
There's no single, universal cut-off; the credit score required for education loan approval varies by lender, loan amount, and whether the loan is secured or unsecured. Here’s general market guidance:
| Score Range | What It Generally Means |
|---|---|
| 750+ | 750+ Strong approval chances & best interest rates |
| 700–749 | Good chances & competitive rates |
| 650–699 | May need a stronger co-applicant or collateral |
| 600–649 | Digital/fintech lenders, high rates, lower ticket size |
| 650 | High rejection risk, alternative routes recommended |
Government-backed schemes work differently from private-lender criteria and are worth exploring if your score falls short of a bank's benchmark. These schemes typically ease the credit burden on the co-applicant by providing government backing. For example, the PM Vidyalaxmi Scheme offers collateral-free, guarantor-free loans to students admitted on merit, along with a partial credit guarantee to banks and an interest subvention for lower-income families.
How Does an Education Loan Affect Your Credit Score?
Whether an education loan affects your credit score going forward depends entirely on how it's repaid. Timely payments and missed ones both leave a lasting mark, in opposite directions.
Repaying Your Education Loan on Time Builds Your Credit History Early
An education loan is often a student's first exposure to credit. Most lenders in India offer a moratorium period, typically the course duration plus a further six to twelve months, during which full EMI payments aren't required. Interest still accrues during this time, and some lenders allow (or expect) interest-only payments even before the moratorium ends. Once regular EMIs begin, paying on time, every time, steadily builds a strong credit history well before you enter the workforce.
A Good Credit Mix: Why Having an Education Loan Works In Your Favour
Credit mix is a recognised factor in how your score is calculated, alongside payment history and credit utilisation, though it carries less weight than either. It looks at whether you can responsibly manage different types of credit: secured loans like home or auto loans, and unsecured ones like credit cards or personal loans. An education loan, secured or unsecured depending on its terms, adds to this mix and can work in your favour later, when you apply for a car loan or credit card in the future.
Defaulting or Missing EMIs, The Impact on Your Score and Your Co-applicant's
A missed EMI doesn't take long to show up on your credit report. Lenders track how many days a payment is overdue, and once it crosses a set threshold, it's reported as past due to credit bureaus and stays on record for years. Because most education loans are co-applied, this reporting affects both the students' and the co-applicants ' scores, potentially affecting their ability to get approved for a car loan, credit card, or another loan.
Even one missed EMI at this stage can cause lasting damage, read exactly how a late payment impacts your credit score and how long it stays on your report."
From the Bureau's Desk
At CRIF HighMark, we see education loans reported to our bureau from the first EMI. Your repayment behaviour starts building, or damaging, your credit record from month one. Students who repay consistently enter the job market with a strong credit profile. Those who miss even one EMI at this stage often find their first post-graduation loan application rejected.
What to Do If Your Credit Score Is Too Low for an Education Loan
A low score isn't the end of the road. A few practical options can still improve your chances:
- Apply with a stronger co-applicant: A parent or guardian with a healthier credit history[PR14.1] and stable income can shift the outcome of the entire application.
- Offer collateral: For larger loan amounts, pledging property or a fixed deposit can offset a weaker credit profile and make lenders more willing to sanction the loan.
- Explore government-backed schemes: Such programmes often apply different eligibility criteria than private lenders, offering collateral-free or guarantor-free options backed by a government credit guarantee.
If you need credit urgently while your score is still recovering, read our guide to getting a personal loan with a low credit score.
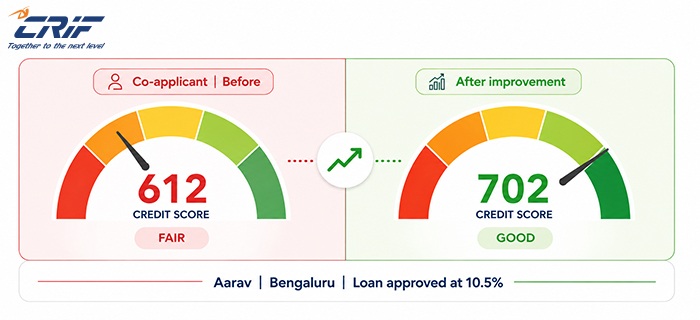
Aarav, a 23-year-old engineering graduate from Bengaluru, was rejected for an ₹8 lakh MBA loan because his father, the co-applicant, had a score of 612 from an old unpaid credit card balance.
What they did:
- Cleared the ₹18,000 overdue balance
- Waited five months for the score to update
- Re-applied at a score of 702
Result: approved at 10.5% interest, down from the 12.5% first quoted.
Your Credit Score Is Part of Your Application, Not an Afterthought
Getting an education loan approved isn't just about the course or the college; it's about what your credit report and your co-applicant's say about you before you even apply. A little planning ahead of time, checking scores early, choosing the right co-applicant, and exploring government-backed options where needed can be the difference between a rejection and a lower interest rate. The earlier you treat your credit score required for an education loan approval, the smoother the rest of the process is likely to be.
Frequently Asked Questions
1. What is the minimum credit score for an education loan in India?
There's no fixed minimum; it varies by lender, but a score of 700 or above is generally seen as favourable, while scores below 650 face a higher risk of rejection.
2. Can I get an education loan with a low or no credit score?
Yes. Applying with a co-applicant who has a stronger credit profile, or exploring government-backed schemes, can improve your chances even with a low or no credit file.
3. Does my parents' credit score affect my education loan application?
Yes. Since most education loans require a parent or guardian as a co-applicant, lenders assess their credit score and repayment history alongside the student's.
4. Does repaying an education loan improve my credit score?
Yes. Consistent, on-time EMI payments build a positive repayment history, can improve your score over time, and add to your credit mix.
5. What happens to my credit score if I default on an education loan?
A default or missed EMI can lower both the student's and the co-applicant's credit score, and may affect future loan or credit card approvals for both.
Disclaimer: This article is intended for general educational purposes only and should not be considered financial or legal advice. Credit reporting timelines, CRIF Credit Score calculations, and lender policies may vary. Always verify your account details with your lender and refer to your latest CRIF HighMark credit report for the most accurate information.
Written by: CRIF Editorial Team | Published: August 2026 | Last Updated: August 2026