Which Debts Should I Pay Off First to Improve My Credit?
Short Answer - To boost your credit, pay off debts with high credit utilisation first—usually credit cards near their limits. Focus on accounts that are maxed out or have the highest interest rates, and always pay at least the minimum on all others to avoid late payments.
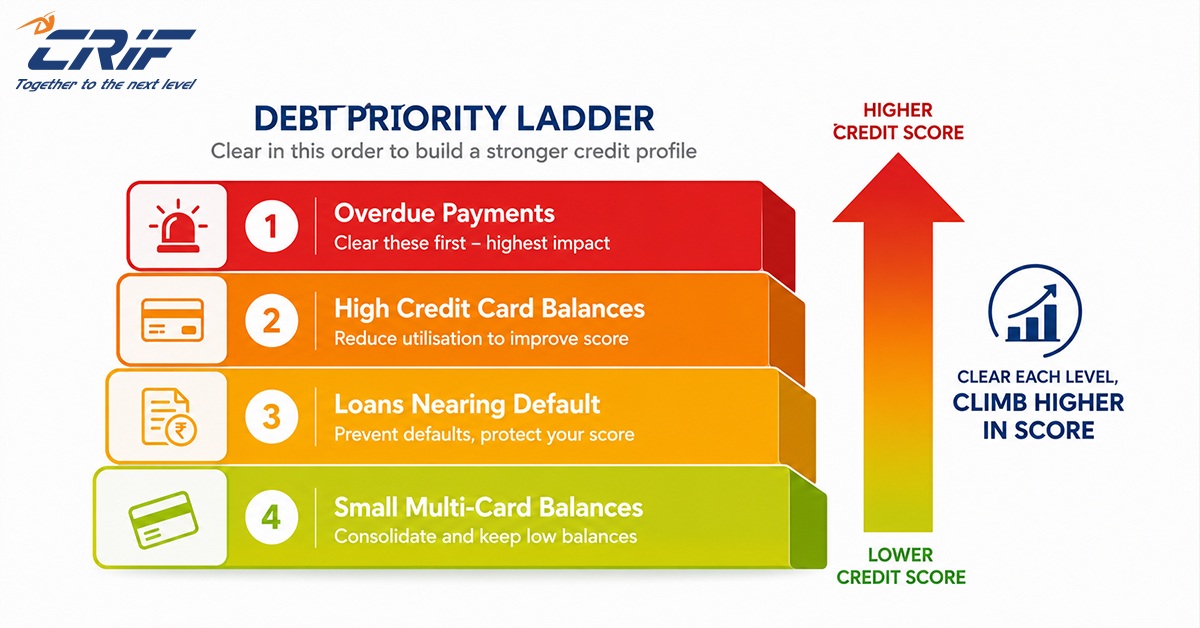
One of the best ways to pay off debt and raise your credit score is to prioritise debts based on the damage they're causing to your credit profile, rather than simply tackling whichever balance feels most urgent. Overdue payments, high credit card utilisation, and accounts nearing default each affect your score differently. By focusing on the right debts first, you can reduce credit damage and start seeing improvements sooner.
How Your Debts Affect Your Credit Score Differently
Not all debt affects your credit score in the same way. Missed or overdue payments hurt your payment history, which is the most important scoring factor. High credit card balances increase your credit utilisation ratio, signalling greater reliance on credit and lowering your score[PR3.1]. Written-off or defaulted accounts cause the most severe damage, remaining on your credit report for years and affecting your ability to access new credit.
Which Debts Should You Pay Off First?
Prioritising the right balances between different debts can help you reduce credit score damage, improve your financial position faster, and see positive results sooner.
High-Interest Credit Card Balances
Once you've got overdue accounts under control, focus on credit cards with the highest balances relative to their credit limits. This is often where you can see a quicker improvement in your credit score, as lowering your balances can improve your credit utilisation ratio within a billing cycle or two. It’s also a good idea to prioritise high interest debt, since paying it down reduces the interest you pay while also lowering your utilisation ratio.
For a deeper understanding of the credit utilisation ratio and how it works, see our dedicated guide on the credit utilisation ratio
Debts With Missed or Overdue Payments
Payment history carries more weight in your credit score than any other factor, so an overdue account is actively working against you for as long as it remains unpaid. Even a relatively small overdue balance can have a disproportionate impact on your score. Therefore, if you're dealing with a delayed unpaid debt situation, bringing that account up to date should be your top priority before focusing on other debts, including high-interest credit card balances.
From the Bureau's Desk:
At CRIF Highmark, we consistently see payment history as the single biggest driver of score damage and recovery. Getting overdue accounts back on track is always the first move.
Small Balances Across Multiple Credit Cards
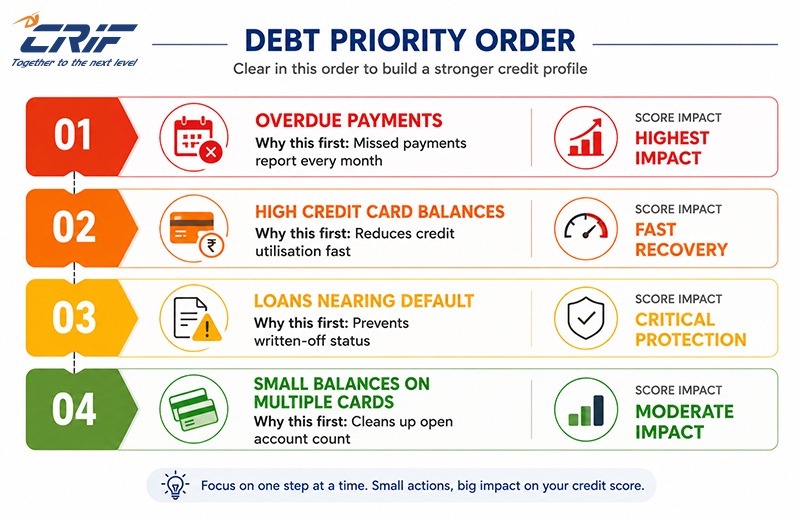
Once overdue accounts and high utilisation are under control, you can work through smaller balances across multiple cards. Clearing them can simplify repayments and reduce your overall credit utilisation, as long as you keep all other repayments on time.
Loans Nearing Default
Address a loan close to default before it reaches that stage. Missed payments can already hurt your credit score, but once an account is written off or marked as a default, the damage becomes much more severe and can remain on your credit report for years. Taking action early can help prevent long-term credit damage and give you more repayment options.
If you're considering combining multiple debts to make repayments more manageable, read our guide on how debt consolidation affects your credit score before making a decision.
From the Bureau's Desk:
A written-off account does not disappear from your credit report simply because you later repay or settle the outstanding amount. Any change in account status is based on information reported by the lender. If you settle an account, the lender should report the updated status to the credit bureau.
What About Long-Term, Low-Interest Loans?
Home loans and education loans are typically long-term, lower-interest debts, so they don't usually require the same urgency as overdue accounts, high-utilisation credit cards, or loans nearing default. As long as repayments are being made on time, they're unlikely to be the biggest factor affecting your credit score.
Avoid skipping EMIs to pay off another debt faster. Redirecting money from a home loan or education loan to a credit card balance can create a new missed-payment issue on an account that was previously in good standing. In most cases, it's better to stay current on these loan repayments while putting extra funds toward higher-priority debts.
How to Stay Consistent With Debt Repayments
Getting the repayment order right matters, but staying consistent is what protects the progress you make over time. Here’s how you can stay consistent with your debt repayments:
- Set Up Auto-Debit for All Your EMIs: Missed payments are rarely intentional; they're often the result of a forgotten due date. Setting up auto-debit reduces this risk and helps maintain a strong payment history, which is the most important factor in your credit score.
- Track Your Credit Score Every 3 Months: Reviewing your credit score every quarter helps you see which debt repayments are actually improving your credit profile. This allows you to make more informed decisions about where to direct your next payment instead of relying on guesswork.
Case Study: How Deepak Rebuilt His Score by Prioritising the Right Debts
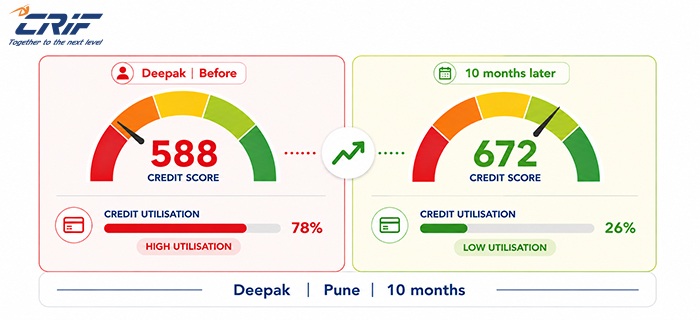
Deepak, a 29-year-old accountant in Pune, was managing three debts at once: a credit card with a ₹45,000 balance on a ₹50,000 limit (90% utilisation), a personal loan of ₹1.2 lakh with regular EMIs, and a written-off two-wheeler loan of ₹35,000. His credit score sat at 588.
What he did: He paid down ₹20,000 on the credit card first, bringing utilisation to 50% and then to 40% over three months. At the same time, he contacted the lender on the written-off loan and settled it for ₹28,000, while continuing his personal loan EMIs without a single miss
Result: His score climbed from 588 to 672 over 10 months.
The Right Debt Repayment Order Matters
Not all debts affect your credit score equally, which is why the order in which you repay them can make a real difference. If you're wondering what debt to pay off first to improve credit score, start with overdue accounts, then focus on high-utilisation credit cards and loans nearing default. By prioritising the debts causing the most damage and staying consistent with repayments, you can improve your credit profile more effectively and see results sooner.
If your score has already taken a hit and you need credit now, read our guide to getting a personal loan with a low credit score, including what lenders actually look for.
Frequently Asked Questions
1. Does credit score increase when paying off debt?
Not always instantly, but often within the next billing cycle, especially when the debt you clear was pushing up your utilisation or was overdue.
2. Which type of debt hurts your credit score the most?
Missed or overdue payments and written-off accounts cause the most damage, since payment history is the largest factor in your score.
3. Should I pay off credit cards or personal loans first?
If either is overdue, clear that first. Between the two, high-utilisation credit cards usually recover faster than a personal loan on regular EMIs.
4. How long does it take for a credit score to improve after paying off debt?
Utilisation-related improvements can show within a cycle or two. Recovery from missed payments or written-off accounts typically takes several months.
5. Does settling a written-off loan remove it from my credit report?
No. The entry stays on your report for 7 years from when it first went overdue, but the status changes to "settled," which lenders view more favourably than "written off."
Disclaimer: This article is intended for general educational purposes only and should not be considered financial or legal advice. Credit reporting timelines, CRIF Credit Score calculations, and lender policies may vary. Always verify your account details with your lender and refer to your latest CRIF HighMark credit report for the most accurate information.
Written by: CRIF Editorial Team | Published: August 2026 | Last Updated: August 2026